 September 17, 2026 · Expense Manager
Personal financial planning: A step-by-step guide for beginners
Personal financial planning is the process of deciding how to use your income, savings, assets and other financial resources to support your current needs and future goals.
For a beginner, that does not mean you need a complicated spreadsheet, investment portfolio or 30-year forecast.
A practical financial plan can begin with a much simpler sequence:
Understand where you stand → Control your cash flow → Set goals → Build protection → Manage debt → Save and invest → Review regularly
The important part is the order.
Investing before understanding your spending, saving without clear goals or creating an aggressive debt-repayment plan without an emergency buffer can leave different parts of your finances working against each other.
This guide walks through personal financial planning from the beginning so you can build a plan around your actual circumstances rather than follow generic financial rules blindly.
Quick summary
A beginner’s personal financial plan should answer six basic questions:
Where do my finances stand today?
Where does my money go every month?
What am I trying to achieve?
What financial risks could disrupt the plan?
How should I handle savings, debt and investing?
How will I measure whether I am making progress?
A practical financial plan generally covers:
| Area | Question to answer |
|---|---|
| Income | How much money comes in? |
| Expenses | Where does it go? |
| Net worth | What do I own versus owe? |
| Goals | What am I saving or investing for? |
| Emergency fund | How would I handle an unexpected expense? |
| Debt | What do I owe and how will I repay it? |
| Insurance | What financial risks need protection? |
| Savings and investments | How will I fund future goals? |
| Retirement | How will I prepare for life after regular employment income? |
| Review | Is my plan still working? |
Financial planning is not about predicting your future perfectly.
It is about giving your money a direction and updating that direction when your life changes.
What is personal financial planning?
Personal financial planning is the process of assessing your current finances, setting financial goals and creating a structured plan for managing income, expenses, savings, debt, insurance, investments and future financial needs.
The Securities and Exchange Board of India’s personal finance education resources cover the same broad areas, including income and expense management, budgeting, financial goals, debt, insurance, retirement and estate planning.
That breadth matters.
Financial planning is not simply:
“Which investment should I buy?”
Investing is only one part of the plan.
A person with a large investment portfolio but uncontrolled debt, inadequate emergency savings or poor insurance protection may still have a weak financial foundation.
Why is personal financial planning important?
Without a plan, financial decisions are often made individually.
You might:
save whatever remains at the end of the month
invest because someone recommended a product
use credit when an unexpected expense appears
buy insurance without knowing how much protection you need
think about retirement only when it feels close
set vague goals such as “save more money”
A financial plan connects these decisions.
For example:
Track spending → create monthly surplus → build emergency reserves → reduce expensive debt → fund goals → invest for long-term needs
Each part supports the next.
The personal financial planning process
SEBI’s financial-literacy material describes financial planning as a process that begins with understanding your current financial situation, identifying goals and alternatives, implementing a plan and reviewing it over time.
For a beginner, the process can be turned into nine practical steps:
Assess your current financial position.
Understand your income and expenses.
Set specific financial goals.
Create a realistic budget.
Build an emergency fund.
Review and manage debt.
Protect important financial risks.
Save and invest according to your goals.
Review and update the plan.
Let’s go through them in order.
Step 1: Assess your current financial position
Before deciding where you want to go financially, understand where you are now.
Start with four pieces of information:
income
expenses
assets
liabilities
Calculate your net worth
Your net worth is:
Total assets − total liabilities = net worth
Assets might include:
bank balances
fixed deposits
investments
retirement accounts
property
other assets with meaningful financial value
Liabilities can include:
home loan
vehicle loan
education loan
personal loan
credit-card balances
other amounts you owe
Example
Suppose your finances look like this:
| Assets | Value |
|---|---|
| Bank savings | ₹1,50,000 |
| Fixed deposit | ₹1,00,000 |
| Investments | ₹2,00,000 |
| Other financial assets | ₹50,000 |
| Total assets | ₹5,00,000 |
And:
| Liabilities | Amount owed |
|---|---|
| Personal loan | ₹1,20,000 |
| Credit card | ₹30,000 |
| Vehicle loan | ₹2,00,000 |
| Total liabilities | ₹3,50,000 |
Your illustrative net worth would be:
₹5,00,000 − ₹3,50,000 = ₹1,50,000
The purpose is not to compare your number with someone else’s.
It creates a baseline.
You can calculate it again later to see whether your financial position is improving.
Step 2: Understand your monthly cash flow
Net worth tells you where you stand.
Cash flow tells you what is happening every month.
The basic calculation is:
Income − expenses = monthly surplus or deficit
If you earn ₹60,000 and spend ₹52,000, your monthly surplus is ₹8,000.
If you earn ₹60,000 and spend ₹65,000, you have a ₹5,000 deficit that must be funded from savings or borrowing.
That difference determines what your financial plan can realistically support.
Track actual spending before guessing
Many first budgets fail because they are based on what someone thinks they spend rather than what they actually spend.
Record expenses such as:
rent or housing
groceries
utilities
transportation
healthcare
education
EMIs
subscriptions
dining
shopping
entertainment
travel
irregular expenses
If you do not already have accurate spending records, start with our guide on how to track daily expenses on your phone.
SEBI’s guidance on managing income and expenses similarly recommends creating a budget, tracking spending, prioritising basic needs, building emergency reserves and setting money aside for future goals.
Do not forget irregular expenses
A monthly budget can look comfortable until an annual or semi-annual expense arrives.
Examples include:
insurance premiums
vehicle servicing
school fees
festival spending
annual subscriptions
property-related payments
medical costs
travel
A good financial plan anticipates predictable irregular expenses rather than treating every one of them as an emergency.
Step 3: Set clear financial goals
Once you understand your starting point, decide what the money is for.
Financial goals give your savings and investments direction.
Instead of:
“I want to save more.”
use:
“I want to save ₹3,00,000 for a home down payment within three years.”
SEBI’s financial goals and budgeting guidance recommends setting goals that are specific, measurable, achievable, realistic and time-bound.
Organize goals by time horizon
A simple framework is:
| Time horizon | Examples |
|---|---|
| Short term | Emergency fund, vacation, device replacement, small debt payoff |
| Medium term | Car, education, home down payment, starting a business |
| Long term | Retirement, children’s education, long-term wealth goals |
There is no universal definition of exactly how many years count as short, medium or long term.
The important thing is knowing when you will need the money.
That time horizon influences how you save or invest for the goal.
Give every major goal four numbers
For each goal, write down:
amount needed
target date
amount already saved
amount you still need
For example:
Goal: Emergency fund
Target: ₹2,00,000
Current amount: ₹50,000
Gap: ₹1,50,000
Target date: 18 months
Now the goal is measurable.
Step 4: Build a realistic budget around your goals
A financial plan exists at the long-term level.
A budget puts that plan into action every month.
Your monthly income needs to cover some combination of:
Needs + wants + debt + savings + investments + goals
There is no perfect allocation percentage that works for everyone.
Popular frameworks such as the 50/30/20 approach can provide a starting structure, but your actual allocation depends on factors such as:
income
housing costs
family responsibilities
debt
location
health expenses
goals
career stage
The goal is not to force your life into a fixed percentage.
The goal is to make sure your monthly spending reflects your priorities.
Pay yourself deliberately
Do not rely only on:
Income → spend → save whatever is left
Where practical, use:
Income → allocate toward goals → manage remaining spending
This can make savings more intentional.
However, your targets should remain realistic.
If you consistently miss them, adjust the plan using real spending data rather than assuming you lack discipline.
Step 5: Build an emergency fund
An emergency fund is money set aside for genuine unexpected expenses or temporary financial disruption.
Examples may include:
job loss
urgent medical expense
major home repair
essential vehicle repair
temporary loss of income
Its purpose is to reduce the chance that an emergency forces you to:
take expensive debt
sell long-term investments at a poor time
miss essential payments
How much should you keep?
There is no amount that is correct for everyone.
Think about:
monthly essential expenses
income stability
whether your household has one or several incomes
number of dependants
health needs
existing insurance
job security
access to other liquid funds
A freelancer with irregular income may want a different buffer from someone with highly stable employment and multiple household incomes.
Keep emergency money accessible
Emergency money should generally prioritize availability and stability rather than aggressive growth.
It is not the same as your long-term investment portfolio.
SEBI’s investment education guidance recommends maintaining emergency funds before focusing solely on future investments and also highlights the importance of insurance protection. You can review its official guidance on factors to consider before investing.
Step 6: Make a plan for your debt
Debt is part of financial planning because repayments compete directly with saving and investing for your monthly income.
Create a list containing:
| Debt | Balance | Interest rate | Payment | Due date |
|---|---|---|---|---|
| Credit card | ₹40,000 | Example only | ₹4,000 | 5th |
| Personal loan | ₹1,50,000 | Example only | ₹7,000 | 10th |
| Vehicle loan | ₹3,00,000 | Example only | ₹9,000 | 18th |
Then consider:
cost of the debt
required payments
whether it is secured
consequences of missing payments
how much extra you can repay
High-cost debt can significantly affect your ability to save for other goals.
But do not direct so much money toward debt that you cannot meet basic expenses or repeatedly need to borrow again.
A debt plan should fit within your full financial plan.
Step 7: Protect your financial plan with appropriate insurance
Financial planning is not only about growing money.
It is also about protecting against events that could damage years of financial progress.
Insurance needs vary by person, but areas to review can include:
health insurance
life insurance where others depend on your income
vehicle insurance
home/property insurance
other relevant protection
SEBI’s insurance education guidance explains insurance as financial protection against unforeseen events and recommends assessing what you actually need to protect.
Insurance should solve a risk problem
Before buying a policy, ask:
What financial risk am I trying to transfer?
For example:
A person with financially dependent children may have a different life-insurance need from someone with no dependants.
Someone relying on one income may need to think differently about financial protection from a household with several independent income sources.
The goal is appropriate protection not simply owning more financial products.
Step 8: Save and invest according to your goals
Once you have reasonable control over cash flow, essential protection and debt, you can connect your long-term goals to appropriate saving and investment strategies.
Investment decisions should consider:
goal
time horizon
risk tolerance
liquidity needs
diversification
fees and costs
taxes
personal circumstances
SEBI’s investment guidance explains that asset allocation should reflect factors such as financial goals, risk tolerance and time horizon. It also emphasizes diversification and regular portfolio review.
Different goals can require different approaches
Money needed in the near future has a different job from money intended for retirement decades away.
That means one investment approach does not automatically suit every goal.
Instead of starting with:
“Which investment gives the highest return?”
start with:
“When do I need this money, how much risk can I reasonably accept and what role does this money play in my overall plan?”
Do not invest in products you do not understand
Before investing, understand:
how the product works
major risks
fees
lock-in or liquidity conditions
potential tax implications
who regulates it
Avoid making decisions only because an investment is popular or because someone promises unusually high returns.
Where individualized investment advice is needed, consider an appropriately qualified and regulated professional.
Step 9: Start retirement planning earlier than retirement
Retirement planning is simply the process of preparing for a period when regular employment income may reduce or stop.
The earlier you begin, the more time you have to adjust:
saving levels
investment contributions
retirement expectations
spending assumptions
When planning for retirement, consider:
expected retirement age
current living expenses
inflation
healthcare costs
existing retirement assets
expected sources of income
lifestyle expectations
SEBI’s retirement planning guidance encourages planning early, preparing for unplanned expenses and considering diversification.
You can also use SEBI’s official financial planning calculators to explore financial goals, net worth, compounding and retirement scenarios.
These calculators are planning tools, not predictions of guaranteed future outcomes.
Step 10: Review nominations, beneficiaries and estate planning
This step is often ignored by beginner guides.
Financial planning is not complete if nobody knows what should happen to your assets when you cannot manage them yourself.
Depending on your circumstances, this may involve reviewing:
nominees or beneficiaries
important account information
insurance nominations
a will
power of attorney arrangements
ownership records
SEBI’s estate planning overview explains the basic role of wills and estate planning and recommends reviewing arrangements as life circumstances change.
Estate laws vary by jurisdiction, so professional legal advice may be appropriate for significant or complex estates.
A beginner financial plan example
Consider this illustrative example.
Rohan is 27 and earns ₹65,000 per month after deductions.
His current monthly spending is:
| Category | Amount |
|---|---|
| Rent | ₹15,000 |
| Food and groceries | ₹9,000 |
| Transport | ₹4,000 |
| Utilities | ₹3,000 |
| EMI | ₹7,000 |
| Shopping/entertainment | ₹8,000 |
| Other expenses | ₹5,000 |
| Total | ₹51,000 |
That leaves approximately ₹14,000 before irregular costs.
Instead of immediately investing the entire ₹14,000, he reviews his complete situation.
He discovers:
his emergency savings are small
he has outstanding high-cost credit-card debt
he wants a home down payment in five years
he has employer health coverage but needs to review his overall insurance needs
he has not started planning seriously for retirement
A reasonable planning sequence might therefore be:
First: Track actual spending for several months.
Second: Build an appropriate emergency reserve.
Third: Create a structured plan for expensive debt.
Fourth: Define the home goal with an amount and target date.
Fifth: Review insurance needs.
Sixth: Build goal-based saving and investment plans appropriate to his circumstances.
Seventh: Review the plan periodically.
This is an example of process, not a personalized financial recommendation.
The important insight is that financial decisions should work together.
How Expense Manager can support personal financial planning
A financial planning app does not need to make investment decisions for you to be useful.
One of the most important inputs to any financial plan is accurate cash-flow information.
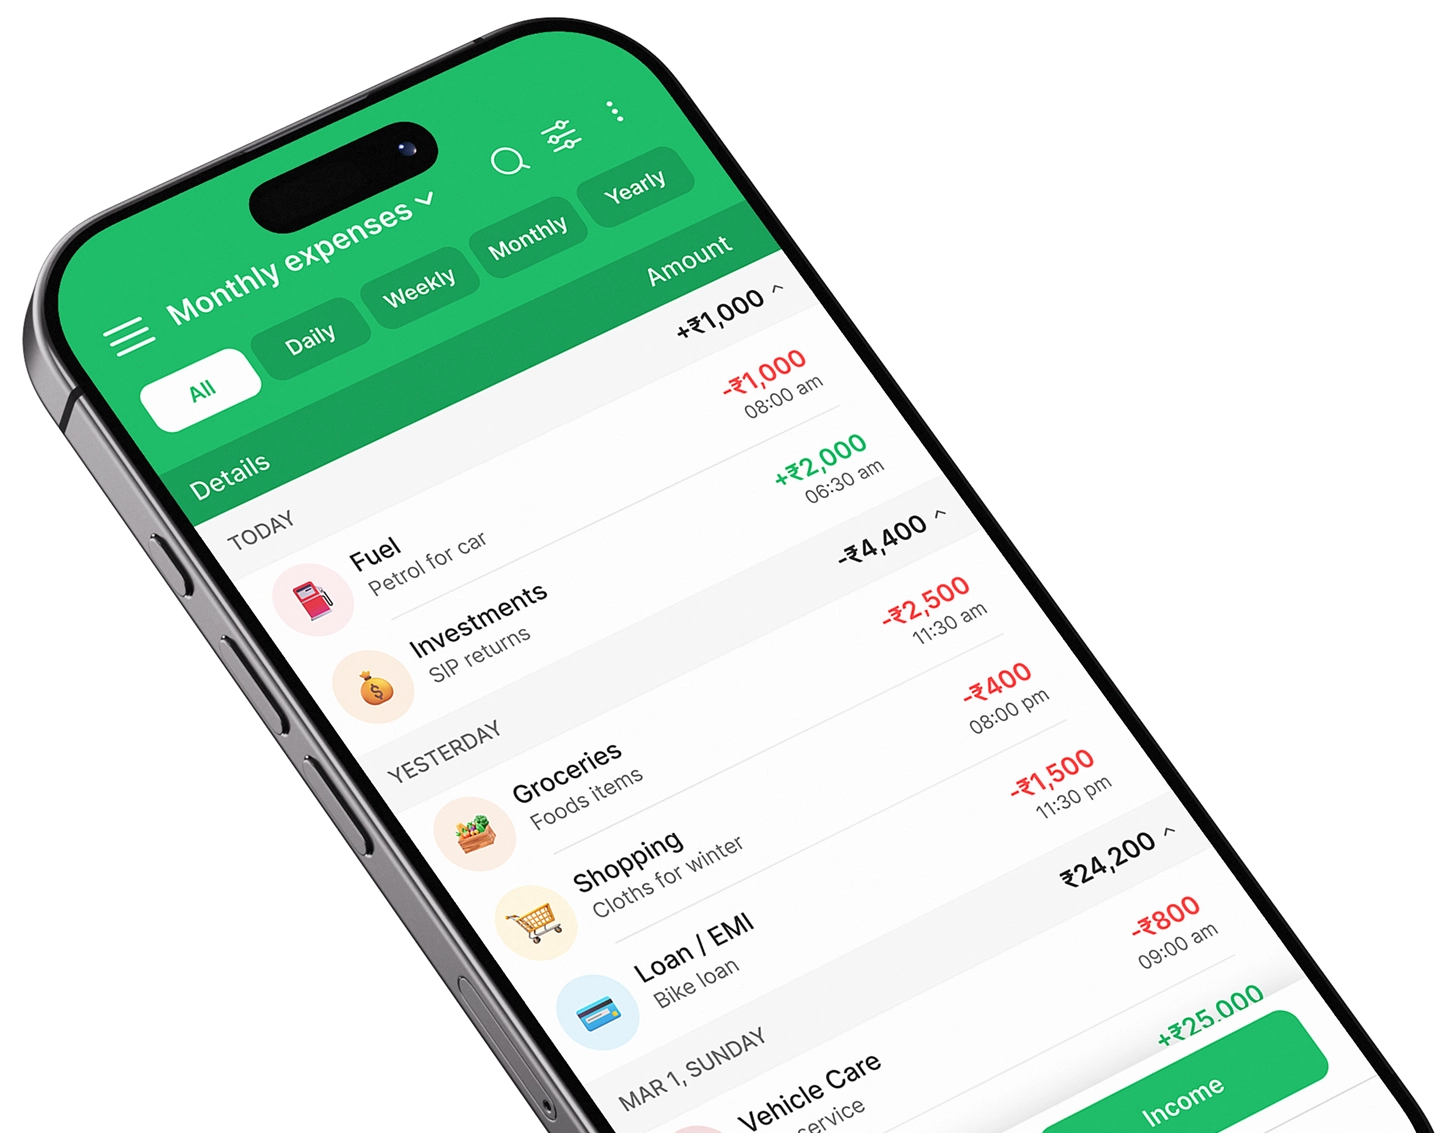
Expense Manager helps users record income and expenses, organize transactions into categories, manage multiple accounts and review financial activity through charts and reports.
Its current features include:
income and expense tracking
custom categories and subcategories
multiple accounts
daily, weekly, monthly and yearly views
income-versus-expense charts
category-wise analysis
account-specific reports
PDF and Excel exports
period comparisons
You can verify these features on the Expense Manager FAQ.
For financial planning, that information can help answer practical questions such as:
What are my average monthly expenses?
Which spending categories are increasing?
How much surplus do I usually have?
Is my budget realistic?
Am I consistently saving money?
How much does lifestyle spending vary month to month?
If you are comparing ways to maintain those records, you can also review our guide to the best expense manager apps.
Expense Manager does not replace regulated investment, tax, insurance, debt or legal advice.
Its role is to make the everyday financial data behind your plan easier to record and understand.
How often should you review your financial plan?
A plan should not be written once and forgotten.
A useful schedule is:
Monthly
Review:
income
expenses
budget performance
debt payments
savings contributions
Quarterly
Review:
progress toward major goals
net worth
unusual spending changes
debt balances
emergency reserves
Annually
Review the broader plan:
goals
insurance
investment strategy
retirement planning
nominations
tax considerations
major upcoming expenses
After a major life event
Review your plan when something significant changes, such as:
marriage
birth of a child
job change
major income increase or decrease
home purchase
business launch
inheritance
major health event
retirement
The purpose of reviewing is not to constantly change the plan.
It is to make sure the plan still reflects your life.
Common financial planning mistakes beginners make
Starting with investments instead of cash flow
Investing is difficult to sustain if you continually run short of money.
Better approach: Understand income and spending first.
Setting vague financial goals
“Save more” provides no target.
Better approach: Define an amount and timeline.
Ignoring emergency expenses
Without accessible reserves, one emergency can disrupt long-term plans.
Better approach: Include financial resilience in the plan.
Following someone else’s budget percentages exactly
Rules such as 50/30/20 can be useful frameworks but cannot account for every household.
Better approach: Base allocations on your real expenses, responsibilities and goals.
Ignoring debt while investing aggressively
The cost and terms of debt can materially affect your financial position.
Better approach: Review debt and investing together rather than treating them independently.
Buying financial products without understanding their purpose
A financial product should solve a specific problem in your plan.
Better approach: Start with the goal, then evaluate suitable options.
Ignoring insurance
One major uninsured event can affect savings accumulated over years.
Better approach: Review meaningful financial risks.
Never reviewing the plan
Income, family circumstances, inflation, goals and financial products change.
Better approach: Schedule regular reviews.
Do you need a financial planner?
Not everyone needs professional financial planning immediately.
Many beginners can start themselves by:
tracking income and spending
calculating net worth
setting goals
creating a budget
understanding debt
building basic financial records
Professional help may be useful when your situation involves:
complex investments
significant assets
retirement decisions
tax complexity
estate planning
business ownership
multiple competing goals
major life transitions
difficulty assessing investment risk
For investment advice in India, verify that the professional is appropriately regulated. SEBI provides information on investment advisers and other investor-protection resources.
Personal financial planning checklist
Before considering your initial plan complete, check whether you can answer these questions:
| Question | Done? |
|---|---|
| Do I know my monthly income? | ☐ |
| Do I know my average monthly expenses? | ☐ |
| Have I calculated my assets and liabilities? | ☐ |
| Do I know my approximate net worth? | ☐ |
| Have I listed my financial goals? | ☐ |
| Does each important goal have an amount and date? | ☐ |
| Do I have a realistic monthly budget? | ☐ |
| Have I considered emergency expenses? | ☐ |
| Do I know all my debts and repayment obligations? | ☐ |
| Have I reviewed major insurance needs? | ☐ |
| Do my savings/investments have a clear purpose? | ☐ |
| Have I started thinking about retirement? | ☐ |
| Have I reviewed nominees/beneficiaries where relevant? | ☐ |
| Do I know when I will review the plan again? | ☐ |
If several answers are “no,” that is not failure.
Those unanswered questions simply tell you what to work on next.
Frequently asked questions
What is personal financial planning?
Personal financial planning is the process of assessing your finances, setting goals and deciding how to manage income, expenses, debt, savings, insurance, investments and future financial needs. The plan should be reviewed as your circumstances change.
What is the first step in financial planning?
Start by understanding your current financial position. Record your income, expenses, assets and liabilities so you know your cash flow and approximate net worth before setting future targets.
What are the main components of a personal financial plan?
A comprehensive plan can include cash-flow management, budgeting, financial goals, emergency savings, debt management, insurance, saving, investing, retirement and estate planning. Not every person needs the same level of complexity in every area.
How do I create a financial plan as a beginner?
Begin by tracking your money, calculating your net worth and setting measurable goals. Then create a realistic budget, build financial protection, address debt and connect savings or investments to specific goals.
Do I need a lot of money to start financial planning?
No. Financial planning is about deciding how to use the resources you currently have. Someone with a modest income can still track expenses, build a budget, set goals and improve financial habits.
How often should I review my financial plan?
Review everyday money management monthly, progress toward major goals periodically and the complete plan at least annually. Major life events should also trigger a review.
Is budgeting the same as financial planning?
No. Budgeting focuses mainly on how income is spent and saved over a shorter period. Financial planning is broader and connects budgeting with goals, debt, protection, investments, retirement and other future needs.
Is investing the same as financial planning?
No. Investing is one component of financial planning. A complete financial plan also considers cash flow, debt, emergency reserves, insurance, goals and other financial responsibilities.
How can expense tracking help with financial planning?
Expense tracking provides real information about where your money goes. That makes it easier to build realistic budgets, identify surplus cash, plan savings and measure whether your financial plan is working.
Can I create a financial plan without a financial adviser?
Many beginners can create a basic plan independently. Professional advice can become useful when investments, taxes, estate planning, retirement or other financial decisions become complex or require individualized recommendations.
Conclusion
Personal financial planning does not begin with finding the perfect investment.
It begins with understanding your money.
Know what you earn.
Know what you spend.
Know what you own and owe.
Then define what you want your money to accomplish.
From there, build the rest of the plan in a sensible sequence:
Cash flow → Goals → Budget → Emergency protection → Debt → Insurance → Saving and investing → Retirement → Review
You do not need to complete every step in a single weekend.
A useful financial plan develops over time as your income, responsibilities and goals change.
The most important thing is that your decisions become connected rather than random.
If you want clearer data about your everyday income and spending before building your plan, Expense Manager can help you track transactions, categorize spending and review your cash flow from one place.
Good financial planning starts with visibility and improves through consistent action.
Author bio
The Expense Manager editorial team creates practical educational content about expense tracking, budgeting, saving and everyday personal finance. Expense Manager is developed by Pavans Group Techsoft Private Limited.
This article provides general educational information only. It does not constitute individualized investment, financial, tax, insurance or legal advice.
Take control of your finances
Download Expense Manager and start your smarter money journey today.


You May Also Like
What is personal finance management? A beginner’s guide