 September 16, 2026 · Expense Manager
What is debt management? A beginner’s guide to managing debt
Debt management is the process of understanding what you owe, organizing repayments, controlling spending and following a realistic plan to reduce debt over time.
For some people, that may mean creating a budget, tracking expenses and paying extra toward a high-interest credit card. For others, it may involve contacting lenders or getting help from a qualified debt adviser or credit counselor.
One distinction is important from the beginning:
Debt management is not the same thing as a formal Debt Management Plan (DMP).
Debt management is the broader process of controlling and repaying debt. A DMP is one specific repayment arrangement available in certain countries and circumstances.
For most beginners, managing debt starts by answering four questions:
How much do I owe?
What does each debt cost me?
How much can I realistically repay each month?
Which debt should I deal with first?
This guide explains how to turn those answers into a practical debt-management system.
Quick summary
Debt management means creating a structured way to control and repay your debts while keeping everyday finances sustainable.
A basic debt-management process usually involves:
listing every debt
recording balances, interest rates and payment dates
understanding your monthly income and expenses
keeping essential payments up to date where possible
choosing an appropriate repayment strategy
directing available extra money toward selected debt
tracking spending and repayment progress
limiting unnecessary new borrowing
reviewing your plan regularly
seeking qualified help when payments become unmanageable
Two commonly used repayment approaches are the debt avalanche method, which prioritizes higher-interest debt, and the debt snowball method, which prioritizes smaller balances.
Neither approach can fix an unaffordable monthly budget by itself. Debt repayment needs to work alongside your income, essential expenses and other financial obligations.
What is debt management?
Debt management is the organized process of tracking, prioritizing and repaying money you owe while keeping your wider finances sustainable.
It can include:
budgeting
expense tracking
keeping a debt inventory
scheduling repayments
prioritizing debts
reviewing interest costs
contacting creditors
consolidating or refinancing debt where appropriate
getting professional debt advice when needed
The purpose is not simply to make this month’s payment.
Good debt management gives you a clear answer to questions such as:
How much do I owe in total?
Who do I owe?
What interest rates am I paying?
When is each payment due?
Which debts are becoming more expensive?
What could happen if I miss a payment?
How much can I afford to repay?
Is my overall debt balance actually falling?
The Reserve Bank of India’s financial education guidance on borrowing makes an important distinction: borrowed money is not income, and repayment ability should be considered before taking on debt. It also warns about repeatedly borrowing to repay earlier loans, which can contribute to a debt trap.
Why is debt management important?
Debt can become difficult to understand when several financial commitments overlap.
You may have:
a home or vehicle EMI
a personal loan
multiple credit cards
buy-now-pay-later payments
education-related debt
everyday household bills
irregular expenses
emergency costs
When everything is handled payment by payment, it is easy to lose sight of the overall financial picture.
It helps you see your real financial position
A bank balance does not tell you how much money is genuinely available.
You might have ₹50,000 in your account but also have ₹35,000 of rent, bills, loan instalments and credit-card payments due before your next salary.
Understanding your cash flow is therefore a core part of managing debt.
If you currently rely mostly on your bank balance to judge affordability, start by tracking your daily expenses and comparing them with your actual income.
It can reduce missed payments
Keeping payment amounts and due dates in one place makes it easier to plan ahead rather than reacting when a payment reminder arrives.
It reveals the real cost of debt
Two debts with similar balances can cost very different amounts depending on:
interest rate
fees
repayment term
penalty charges
whether the rate is fixed or variable
It helps you decide where extra money should go
Once you understand the cost and consequences of each debt, you can make a more deliberate decision about where additional repayments may have the greatest benefit.
It can reveal why debt keeps returning
If you regularly repay one balance but create another, the problem may not be repayment order alone.
Your spending, income, emergency preparedness or use of credit may also need attention.
This is one reason tracking your expenses is useful when building a debt-repayment strategy: you need to understand where the money available for repayment will actually come from.
Debt management is not the same as a Debt Management Plan
People often use these terms interchangeably, but they have different meanings.
Debt management
Debt management is the broad process of organizing and repaying debt.
You can manage debt yourself by:
creating a budget
tracking spending
keeping records of balances and interest rates
making required payments
directing additional repayments strategically
contacting lenders when necessary
Debt Management Plan
A Debt Management Plan, usually abbreviated to DMP, is a particular structured arrangement used in some countries.
For example, the U.S. Consumer Financial Protection Bureau’s credit counseling guidance explains that a credit counselor may help organize a debt management plan in which a consumer makes a payment to the counseling organization and it distributes payments to participating creditors.
In the UK, MoneyHelper’s guidance on Debt Management Plans explains DMPs in the context of certain non-priority debts.
Eligibility, regulation, costs, creditor participation and the types of debts covered vary by country.
So if you are trying to “manage debt,” do not assume that signing up for a formal DMP is automatically the next step.
For many people, the first step is simply understanding their finances properly.
How does debt management work?
A practical debt-management process can be summarized as:
Know → Budget → Prioritize → Repay → Review
Know what you owe
Create one complete list of your debts.
Budget realistically
Understand how much income remains after essential living expenses and required financial commitments.
Prioritize
Consider interest costs, overdue amounts and the consequences of missing payments.
Repay
Follow a repayment strategy you can maintain consistently.
Review
Update your balances, spending and plan as your financial situation changes.
Skipping the first two stages is one reason debt-repayment plans become unrealistic.
Step 1: Make a complete list of your debts
Before deciding which debt to pay first, make a complete debt inventory.
For example:
| Debt | Balance | Interest rate | Required payment | Due date |
|---|---|---|---|---|
| Credit card A | ₹65,000 | 36% | ₹4,000 | 5th |
| Personal loan | ₹1,80,000 | 14% | ₹6,000 | 10th |
| Credit card B | ₹22,000 | 30% | ₹2,000 | 18th |
| Vehicle loan | ₹2,50,000 | 10% | ₹8,000 | 25th |
Example figures only.
For each debt, record:
lender or creditor
current balance
interest rate
minimum or required payment
due date
remaining loan term
whether the debt is secured
relevant fees or penalties
whether payments are currently overdue
Do not rely on memory.
One complete debt list gives you the information needed to compare obligations objectively.
Step 2: Understand your monthly cash flow
You cannot create a realistic debt-repayment plan without knowing how much money is available.
A basic calculation is:
Income − essential expenses − required financial commitments = potential extra repayment capacity
For example:
| Item | Monthly amount |
|---|---|
| Take-home income | ₹70,000 |
| Housing | ₹18,000 |
| Groceries | ₹8,000 |
| Utilities | ₹4,000 |
| Transport | ₹5,000 |
| Healthcare/insurance | ₹3,000 |
| Other essential expenses | ₹7,000 |
| Required debt payments | ₹15,000 |
| Amount remaining | ₹10,000 |
This does not automatically mean the whole ₹10,000 should be sent toward debt.
You may also need to allow for:
annual expenses
dependants
irregular bills
medical needs
upcoming necessary purchases
emergency savings
income fluctuations
The objective is to identify a repayment amount you can maintain without immediately needing to borrow again.
If you do not yet have a spending plan, the guide on how to set a budget that actually sticks provides a useful starting framework.
Step 3: Separate essential spending from flexible spending
Review your recent expenses and divide them into broad groups.
Essential expenses
These might include:
housing
groceries
essential utilities
necessary transport
healthcare
insurance
education commitments
required debt payments
Flexible expenses
Depending on your circumstances, these might include:
frequent dining out
entertainment
optional subscriptions
discretionary shopping
non-essential upgrades
impulse purchases
Reducing some flexible spending may create additional room for debt repayment.
But an extreme budget that you cannot maintain is unlikely to work for long.
The aim is not to eliminate every enjoyable expense.
It is to identify spending that matters less to you than becoming debt-free.
An expense tracker and a budget planner perform different jobs: a budget tells you how you intend to use your money, while expense tracking helps you see what actually happened.
Using both can make a repayment plan more realistic.
Step 4: Decide which debts need priority
One common rule is:
Pay the highest-interest debt first.
That can make mathematical sense when deciding where extra repayments should go, but interest rate should not be the only consideration.
Some unpaid obligations can have more serious consequences than others.
Depending on the debt and your jurisdiction, missed payments can potentially lead to:
loss of an essential asset
utility problems
collection activity
legal action
additional charges
damage to your credit history
Before making aggressive extra payments toward one account, make sure you understand the consequences of falling behind on others.
A useful priority review considers:
consequences of non-payment
whether the debt is secured
overdue status
interest rate
fees and penalties
required monthly payment
outstanding balance
If you are already missing essential payments or facing legal, repossession, foreclosure or serious collection action, individualized professional guidance may be more useful than a generic debt-payoff method.
Step 5: Choose a debt repayment strategy
Once required obligations are accounted for, you can decide how to use any additional repayment money.
Two of the best-known methods are the debt avalanche and debt snowball.
What is the debt avalanche method?
The debt avalanche method directs extra repayment toward the debt with the highest interest rate while required payments continue on the others.
After that debt is cleared, the money previously directed toward it moves to the next-highest-interest debt.
For example:
| Debt | Balance | Interest rate |
|---|---|---|
| Credit card A | ₹50,000 | 36% |
| Credit card B | ₹20,000 | 28% |
| Personal loan | ₹1,00,000 | 13% |
Under an avalanche strategy, additional repayment would generally target Credit Card A first because it carries the highest interest rate.
Advantages of the debt avalanche
The main objective is reducing the cost of expensive debt.
When followed consistently, targeting the highest-interest debt first can reduce interest cost compared with a strategy that leaves expensive debt outstanding for longer.
Limitations of the debt avalanche
The first target might have a large balance.
It can therefore take a long time before you completely eliminate an account, even though you are making financially useful progress.
The Consumer Financial Protection Bureau’s guide to reducing debt describes this highest-interest approach alongside the snowball method.
What is the debt snowball method?
The debt snowball method focuses extra repayment on the smallest outstanding balance first.
You continue making required payments on the remaining debts.
Once the smallest balance is repaid, you direct the freed-up payment toward the next-smallest debt.
Using the same example:
| Debt | Balance | Interest rate |
|---|---|---|
| Credit card A | ₹50,000 | 36% |
| Credit card B | ₹20,000 | 28% |
| Personal loan | ₹1,00,000 | 13% |
A snowball strategy would target Credit Card B first because ₹20,000 is the smallest balance.
Advantages of the debt snowball
Eliminating a smaller debt relatively quickly can provide visible progress and simplify the number of accounts you need to manage.
Limitations of the debt snowball
You may leave higher-interest balances outstanding for longer.
That can increase total interest compared with prioritizing the most expensive debt first.
Debt snowball vs debt avalanche
| Factor | Debt snowball | Debt avalanche |
|---|---|---|
| First target | Smallest balance | Highest interest rate |
| Primary focus | Visible progress | Interest cost |
| Motivation | Earlier account closures may feel rewarding | Progress can feel slower initially |
| Interest efficiency | May cost more | Usually prioritizes reducing expensive interest |
| Suitable for | People motivated by quick wins | People prioritizing financial efficiency |
Neither method is automatically right for everyone.
More importantly, neither should cause you to ignore obligations where missed payments could have more serious consequences.
Step 6: Organize your payment dates
A repayment strategy can fail because of something as simple as poor organization.
Keep a payment calendar containing:
creditor
due date
amount due
payment status
account used for payment
Where practical, reminders or automatic payments can help avoid accidentally missing regular payments.
However, automatic payments should be used carefully if your account balance frequently changes. An automatic debit does not solve a cash-flow shortage.
Step 7: Track your progress every month
Do not measure success only by whether you made this month’s payments.
Track whether your overall financial position is improving.
Review:
total debt outstanding
individual account balances
interest and fees
additional repayment
new borrowing
monthly expenses
income changes
For example:
| Month | Starting debt | New debt | Principal repaid | Ending debt |
|---|---|---|---|---|
| January | ₹3,00,000 | ₹0 | ₹15,000 | ₹2,85,000 |
| February | ₹2,85,000 | ₹5,000 | ₹18,000 | ₹2,72,000 |
| March | ₹2,72,000 | ₹0 | ₹20,000 | ₹2,52,000 |
The “new debt” column matters.
If you are consistently repaying debt but also adding new balances, look beyond your repayment method.
Your income, spending or emergency-expense strategy may also need attention.
Debt management vs debt consolidation
Debt management and debt consolidation are related but different.
Debt management is the overall process of organizing and repaying debt.
Debt consolidation generally means combining multiple debts into one borrowing arrangement or payment.
For example, you might use a consolidation loan to repay several existing debts and then make one payment toward the new loan.
Consolidation can make payments easier to organize, but it does not automatically mean the debt becomes cheaper.
Before consolidating, compare:
interest rate
fees
repayment term
monthly payment
total repayment amount
collateral requirements
variable versus fixed rates
whether you are likely to use the cleared credit again
The CFPB’s current guidance on consolidating credit-card debt notes that a lower monthly payment can sometimes result from a longer repayment period, potentially increasing the total amount paid.
It also recommends understanding why the original debt accumulated.
Moving debt does not solve overspending if spending continues to exceed income.
Debt management vs debt settlement
Debt settlement is also different from ordinary debt management.
Debt settlement generally involves attempting to persuade a creditor to accept less than the full amount owed.
That can involve significant consequences depending on:
your jurisdiction
creditor response
fees
credit reporting
taxes
whether payments are stopped during negotiations
Consumers should be especially cautious about companies promising that they can quickly eliminate or dramatically reduce debt.
The U.S. Federal Trade Commission’s current debt-relief scam guidance warns about providers that demand upfront payment for promised debt-relief services or guarantee fast debt forgiveness.
Rules differ between countries, but the broader lesson is useful:
Be cautious of guaranteed debt-relief promises.
Debt management vs refinancing
Refinancing means replacing an existing loan with a new borrowing arrangement.
It may be useful when the replacement loan genuinely offers more appropriate terms, such as:
a lower interest rate
reasonable fees
a suitable repayment term
a more manageable structure
But a smaller monthly payment does not automatically mean refinancing is cheaper.
A longer repayment period can reduce your monthly instalment while increasing the amount of interest paid over the life of the loan.
Always compare total cost, not just the EMI.
What debts should you pay first?
There is no single repayment order that works for everyone.
A useful framework is:
1. Protect essential living expenses
Your debt strategy should leave enough money for necessities such as housing, food, essential utilities, healthcare and necessary transportation.
2. Consider the consequences of missing payments
Some obligations can create more serious consequences when unpaid.
3. Keep required payments current where possible
Avoid unnecessary arrears, fees and other consequences.
4. Target expensive debt with available extra money
If all critical commitments are covered, higher-interest debt may deserve additional attention.
5. Consider smaller debts when simplification matters
Eliminating smaller balances can reduce the number of payments you need to manage.
The right order may be different if you are already behind on payments or dealing with secured loans or legal action.
Should you save money while paying off debt?
Debt repayment and emergency savings can compete for the same money.
Using every available rupee to repay debt may leave you with no buffer when:
a vehicle needs repair
medical costs arise
an appliance fails
income temporarily falls
Without emergency savings, the next unexpected cost may go straight back onto a credit card or loan.
On the other hand, holding large amounts of cash while paying very high interest on debt can also carry a financial cost.
Factors to consider include:
interest rates
income stability
dependants
insurance
existing savings
upcoming expenses
access to emergency funds
RBI financial-education material also encourages borrowers to use budgeting for repayments and maintain records of repayment schedules and an emergency fund.
The important point is to treat emergency preparedness and debt repayment as connected financial decisions rather than completely separate goals.
How expense tracking helps with debt management
Debt management often looks like a repayment problem.
But the amount you can repay comes from your cash flow.
That means you need to know:
Income → spending → required commitments → available repayment capacity
Expense tracking helps answer questions such as:
How much do I actually spend each month?
Which categories have increased?
Which expenses are essential?
Where am I overspending?
What recurring costs could I review?
How much can I consistently put toward debt?
Am I using debt to cover normal living costs?
Imagine your monthly records show:
| Category | Spending |
|---|---|
| Housing | ₹18,000 |
| Groceries | ₹8,000 |
| Transport | ₹5,000 |
| Utilities | ₹4,000 |
| Dining and delivery | ₹6,500 |
| Shopping | ₹5,000 |
| Subscriptions | ₹2,000 |
Without tracking, you might simply conclude:
“There is never any money left.”
With real spending data, you can identify which categories are essential and which are flexible enough to review.
Expense tracking does not pay off your debt for you.
It gives you the information needed to create a repayment plan based on actual behavior rather than estimates.
If you are new to this process, start with the practical guide on how to track daily expenses on your phone.
How Expense Manager can support your debt-management routine
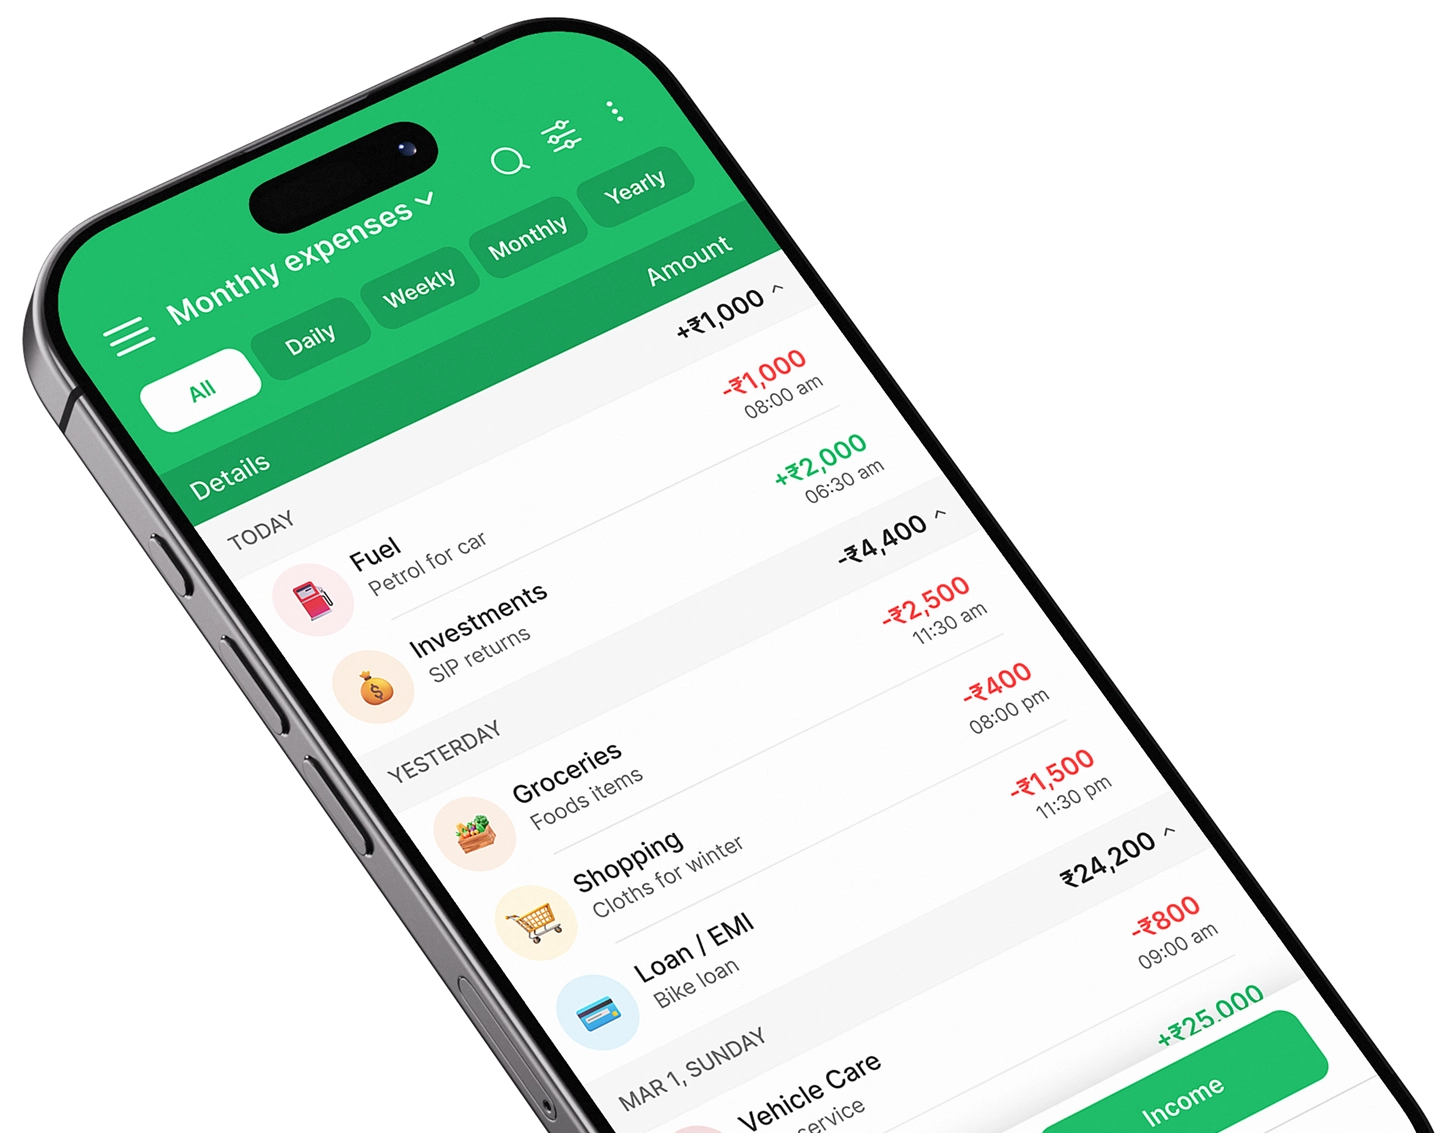
Expense Manager is an income and expense tracking tool. It is not a debt-advice service and does not replace a qualified financial adviser, credit counselor, tax professional or legal adviser.
Its role in debt management is simpler:
help you understand your cash flow and spending.
Expense Manager currently lets users:
record income and expenses
organize transactions by categories and subcategories
maintain multiple accounts
track loan/EMI and credit-card-related expense categories
review daily, weekly, monthly and yearly summaries
analyze category-wise spending
compare income with expenses
review account-specific information
export reports to PDF or Excel
A basic debt-management workflow could therefore look like this:
Record income → Track spending → Review categories → Identify repayment capacity → Make debt payments → Review again
The app does not tell you which debt you should repay first.
That decision depends on your actual debt terms, financial circumstances and, where appropriate, qualified professional advice.
A simple monthly debt-management routine
Debt management becomes easier when it is treated as a regular process rather than an occasional financial emergency.
At the beginning of the month
Review:
expected income
required debt payments
essential household expenses
irregular bills due this month
planned additional repayment
During the month
Track:
everyday spending
debt payments
unexpected costs
new borrowing
Once a week
Check:
upcoming payment dates
remaining budget
discretionary spending
whether your repayment target is still realistic
At the end of the month
Update:
each debt balance
total debt remaining
extra repayment made
interest or fees charged
spending by category
next month’s repayment target
The cycle is:
Plan → Track → Repay → Review → Adjust
That is what sustainable debt management looks like in practice.
Common debt-management mistakes
Not knowing how much you owe in total
Paying bills individually without maintaining one complete list makes strategic planning difficult.
Better approach: Keep an updated debt inventory.
Focusing only on minimum payments
Required payments help you stay on schedule, but paying only minimums may leave expensive revolving balances outstanding for a long time.
Better approach: Where your budget permits, make a deliberate decision about how additional repayment money should be allocated.
Continuing to create new debt
Paying ₹10,000 off one account while adding ₹10,000 elsewhere does not improve your overall debt position.
Better approach: Review why new borrowing keeps occurring.
Looking only at monthly payment size
A loan can have a smaller EMI because its repayment period is longer.
Better approach: Compare total repayment cost, rate, fees and term.
Ignoring due dates
Late payments can add avoidable costs and complications.
Better approach: Maintain reminders or a payment calendar.
Using debt to repay debt without understanding the underlying problem
Consolidation or refinancing can sometimes be useful, but repeatedly replacing old debt with new debt can hide the real issue.
Better approach: Determine whether spending, insufficient income, unexpected costs or another factor caused the original balance.
Creating an unrealistic budget
A repayment target that leaves too little for ordinary life may fail quickly.
Better approach: Build your budget from actual spending records rather than an idealized version of your expenses.
When should you consider professional debt help?
Many people can manage straightforward debts themselves when:
essential expenses remain affordable
required payments are being made
debt is no longer growing
monthly cash flow allows consistent progress
debt terms are understood
Professional help may be appropriate when:
you repeatedly miss payments
debt payments leave too little for essential living costs
you are using new debt to pay existing debt
accounts are seriously overdue
you are facing legal or collection action
you cannot understand the repayment options available
your debt is increasing despite regular payments
The appropriate type of adviser depends on where you live.
In the United States, the CFPB explains the role of credit counseling and notes that counselors can assist with budgeting and debt-management options.
Other countries have different regulatory systems and debt solutions, so use an appropriately qualified or regulated provider for your jurisdiction.
How to evaluate a debt-management or debt-relief provider
Do not choose a company simply because it promises a lower monthly payment.
Before entering an agreement, understand:
what service is actually being provided
whether the provider is appropriately regulated
all fees
which debts are eligible
whether creditors have to participate
what happens to interest
whether payments to creditors will continue
expected duration
cancellation rules
potential effect on your credit
what happens if you cannot make a payment
Be cautious if a company:
guarantees that it can eliminate debt
guarantees unusually large reductions
pressures you to act immediately
hides its fees
tells you to stop communicating with creditors without explaining the consequences
promises a special government debt-forgiveness program without verifiable details
For U.S. readers, the FTC provides detailed guidance on how to get out of debt and identify debt-relief scams.
Frequently asked questions
What is debt management in simple terms?
Debt management means organizing what you owe and following a realistic plan for controlling and repaying it. It usually involves tracking debts, budgeting, making required payments, deciding repayment priorities and reviewing progress regularly.
Is debt management the same as a Debt Management Plan?
No. Debt management is the broader process of managing and repaying debt. A Debt Management Plan is a particular structured repayment arrangement available in some countries and circumstances.
What is the best way to start managing debt?
Start by writing down every debt, including its balance, interest rate, required payment and due date. Then compare your income with your actual essential expenses to understand how much you can realistically put toward repayments.
Should I use the debt snowball or debt avalanche method?
The avalanche method prioritizes the highest-interest debt and generally focuses on reducing interest cost. The snowball method prioritizes the smallest balance and can provide faster visible progress. The right approach depends on your debts, motivation and financial circumstances.
What is the debt snowball method?
The debt snowball method directs extra repayment toward your smallest debt while required payments continue on other debts. Once the smallest debt is cleared, its payment is redirected to the next-smallest balance.
What is the debt avalanche method?
The debt avalanche method directs extra repayment toward the debt with the highest interest rate. Once that debt is eliminated, additional repayment moves to the next-highest-interest debt.
Is debt consolidation the same as debt management?
No. Debt consolidation generally combines multiple debts into another loan or payment arrangement. Debt management is the broader process of organizing, controlling and repaying your debts.
Can an expense tracker help me manage debt?
An expense tracker can help you understand where your money is going and calculate how much may realistically be available for debt repayment. It does not replace debt advice, but better spending visibility can support a more accurate repayment plan.
Can I manage debt without professional help?
Some straightforward debts can be managed through budgeting and a structured repayment strategy. Professional advice may be appropriate when you cannot cover essential costs, are repeatedly missing payments, are facing serious arrears or legal consequences, or do not understand your options.
Does a Debt Management Plan reduce the amount I owe?
Not automatically. Depending on the country and arrangement, a DMP may change the repayment schedule, interest or fees, but it should not be assumed that the original principal will be reduced. Review the exact terms before entering any arrangement.
Conclusion
Debt management is not a quick method for making debt disappear.
It is a structured process for understanding what you owe, protecting essential expenses, organizing repayments and steadily improving your financial position.
For most beginners, the process starts with five actions:
Know what you owe.
Understand where your money goes.
Prioritize your obligations.
Choose a realistic repayment strategy.
Review your progress regularly.
The debt snowball and avalanche methods can both provide useful structures for additional repayment, but repayment order is only one part of the solution.
Your budget, spending habits, emergency preparedness, interest costs and ability to avoid new debt matter too.
If your repayments are already becoming unmanageable, do not simply create a more aggressive budget. Contact your lenders where appropriate and consider guidance from a qualified debt professional familiar with the rules in your country.
For the budgeting and expense-tracking side of the process, Expense Manager can help you record income and expenses, review spending categories and build a clearer picture of the cash flow available for your financial goals.
Better debt management starts with knowing exactly where you stand.
Author bio
The Expense Manager editorial team creates practical guides on expense tracking, budgeting, saving and everyday personal finance. Expense Manager is developed by Pavans Group Techsoft Private Limited.
This article is for general educational purposes and does not constitute individualized financial, investment, tax or legal advice.
Take control of your finances
Download Expense Manager and start your smarter money journey today.

